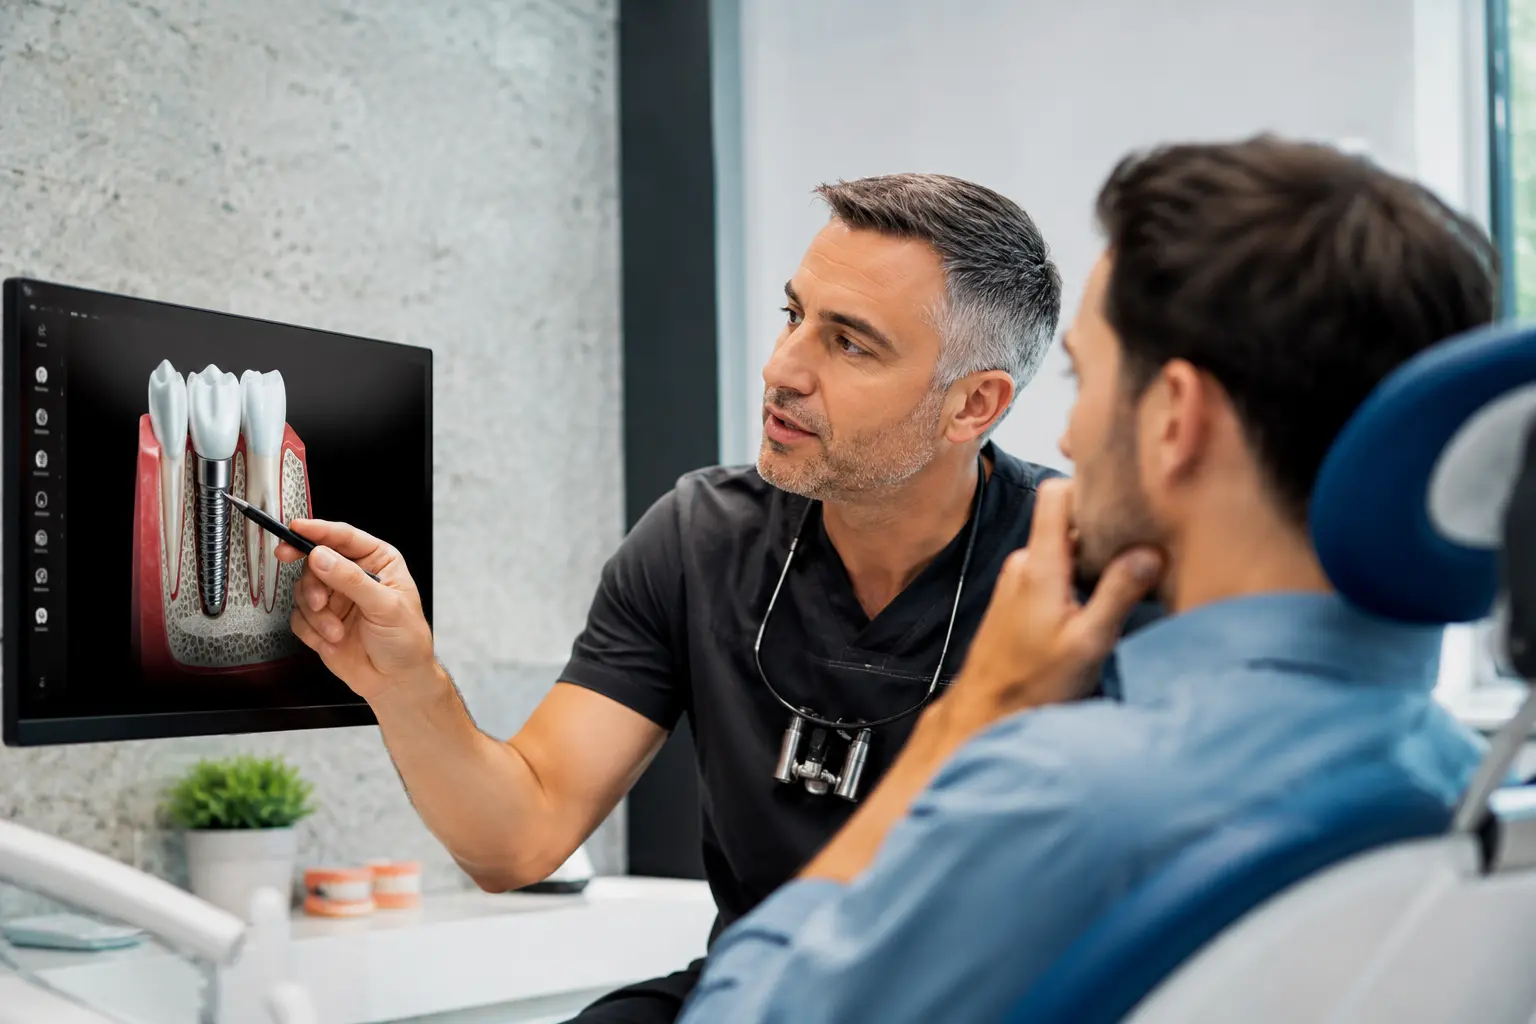
Dental implant cost factors are eating up your budget and you’re terrified you’ll have to choose between affording quality care and keeping your savings intact, but here’s the truth: you don’t have to sacrifice either.
Transparent pricing: unveiling the costs
When you start researching dental implants, the price tags can feel shocking. A single implant might run anywhere from 1500 to 6000 dollars depending on where you live and who performs the procedure. Let’s break down what actually goes into that number. Your consultation and diagnostic imaging, which includes X-rays and sometimes CT scans, can add 200 to 500 dollars before you even commit. Then there’s the implant itself, the abutment, and the crown, each with their own price tag. Materials matter too. Titanium implants are the standard and tend to be more affordable, while zirconia options cost more but appeal to women concerned about metal visibility. If you need bone grafting because your jaw isn’t dense enough, that’s another 500 to 3000 dollars. Some women discover mid-treatment that they need sinus lifts or additional procedures, which can surprise them with unexpected costs. The key is asking your dentist for an itemized breakdown before you sign anything, so you know exactly where every dollar goes.
- Consultation fees and diagnostic tests can add to the overall price.
- The type of implant chosen, such as titanium or zirconia, impacts the cost.
- Complications like infections or the need for further surgeries can drive up expenses.
Insurance coverage: maximizing benefits
Most dental insurance plans treat implants as cosmetic and won’t cover them at all, but don’t assume that’s your situation without checking. Call your insurance provider directly and ask specifically about implant coverage, including whether they cover any portion of the crown, abutment, or extraction. Some plans will cover the extraction of a damaged tooth but not the implant itself. Others, especially if you can document that tooth loss is affecting your ability to eat or speak properly, may classify it as medically necessary and cover 20 to 50 percent. If you have a flexible spending account (FSA) or health savings account (HSA) through your employer, you can use pre-tax dollars to pay for implants, which effectively reduces your out-of-pocket cost by your tax bracket. A woman earning 60,000 dollars annually could save 2000 to 3000 dollars by using her FSA instead of paying with after-tax money. Get your dentist to provide a treatment plan and cost estimate in writing, then submit it to your insurance before starting treatment so there are no surprises.
📘 Fix your day in under 2 minuteschoose where to begin:
Negotiating payment plans: flexible options
Dental offices understand that implants are expensive, and most are willing to work with you on payment. Don’t just accept the first offer. Ask your dentist if they offer in-house payment plans where you pay a portion upfront and the rest over 12 to 24 months, often with little or no interest. Many practices use third-party financing companies like CareCredit or Prosper Healthcare Lending, which offer promotional periods of 6 to 24 months interest-free if you pay the balance within that window. Read the fine print, though, because interest rates after the promotional period can jump to 25 percent or higher. Another strategy is to ask if your dentist will discount the total cost if you pay in full upfront. Some practices offer 5 to 10 percent discounts for cash payments because they avoid credit card processing fees. If you’re having multiple implants done, negotiate on the total package price rather than treating each implant separately. One woman we know negotiated her three implants down by 2000 dollars by offering to pay half upfront and half upon completion, saving her money and giving the dentist confidence in her commitment.
Seeking discounts: special promotions and savings
Dental clinics, especially larger practices and those in competitive markets, run seasonal promotions on implant procedures. Watch for end-of-year specials in November and December when patients are trying to use their annual insurance benefits before they reset. Some practices offer discounts in January and February when they’re slower and want to fill their schedule. Follow dental offices on social media or sign up for their newsletters to catch these deals early. Dental schools and university clinics often perform implants at 40 to 60 percent below market rates because the work is done by students under faculty supervision. The timeline is longer, sometimes taking several months instead of weeks, but the quality is solid and you’re supporting education. Some women also travel to nearby states or countries where dental costs are lower, though you need to factor in travel expenses and the difficulty of follow-up care. If you’re uninsured or underinsured, look into community health centers that offer sliding scale fees based on income. Don’t be shy about asking your dentist directly if they have any current promotions, package deals, or if they’re willing to negotiate on price, especially if you’re a new patient or willing to refer friends.
Research and compare: finding the best value
Getting three to five quotes from different dentists is non-negotiable. You’ll be surprised at the range. One dentist might quote 4500 dollars for a single implant while another quotes 6500 for the exact same procedure. When comparing, make sure you’re looking at the same components: the implant brand, the abutment type, the crown material, and whether any preparatory work like bone grafting is included. Check online reviews on Google, Yelp, and the dentist’s website, but pay special attention to reviews mentioning implant outcomes and how the office handled complications. A dentist with 20 years of implant experience and a 98 percent success rate is worth more than a newer practitioner offering rock-bottom prices. Ask each dentist about their implant brand and whether they use name-brand implants like Straumann or Zimmer, or lesser-known brands that might be cheaper but have fewer long-term studies. Request before-and-after photos of their implant work. Visit the office in person to assess cleanliness, technology, and how the staff treats you. A woman in her 50s spent an extra 1000 dollars going to a highly-reviewed specialist instead of a general dentist, and five years later she’s grateful because her implant has required zero maintenance while a friend’s cheaper implant from a less experienced dentist needed revision surgery.
Understanding dental implant cost factors, maximizing insurance benefits, negotiating payment plans, seeking discounts, and researching multiple dentists are key steps for women looking to cut costs without compromising quality on dental implants.
Are dental implants covered by insurance?
Some insurance plans may cover a portion of the cost of dental implants, especially if the procedure is deemed medically necessary for your oral health. Always call your provider to ask specifically about implant coverage, and check whether you have FSA or HSA benefits available.
Can I negotiate payment plans for dental implants?
Yes, many dental offices offer flexible payment options and installment plans to help patients manage the cost of dental implants more effectively. You can also ask about in-house payment plans, third-party financing, or discounts for upfront payment.
Others also read:
Disclaimer: This article is for informational purposes only and is not a substitute for professional medical advice. Always consult a healthcare professional for personal guidance.
This guide has been prepared and reviewed by the GlobalHealthBeacon editorial team and reflects current medical research as of 2026. It provides structured, evidence-based information to support informed health decisions.
